Tata Sons IPO Row Explained: Why Shapoorji Pallonji Wants a Listing While Tata Trusts Opposes It.
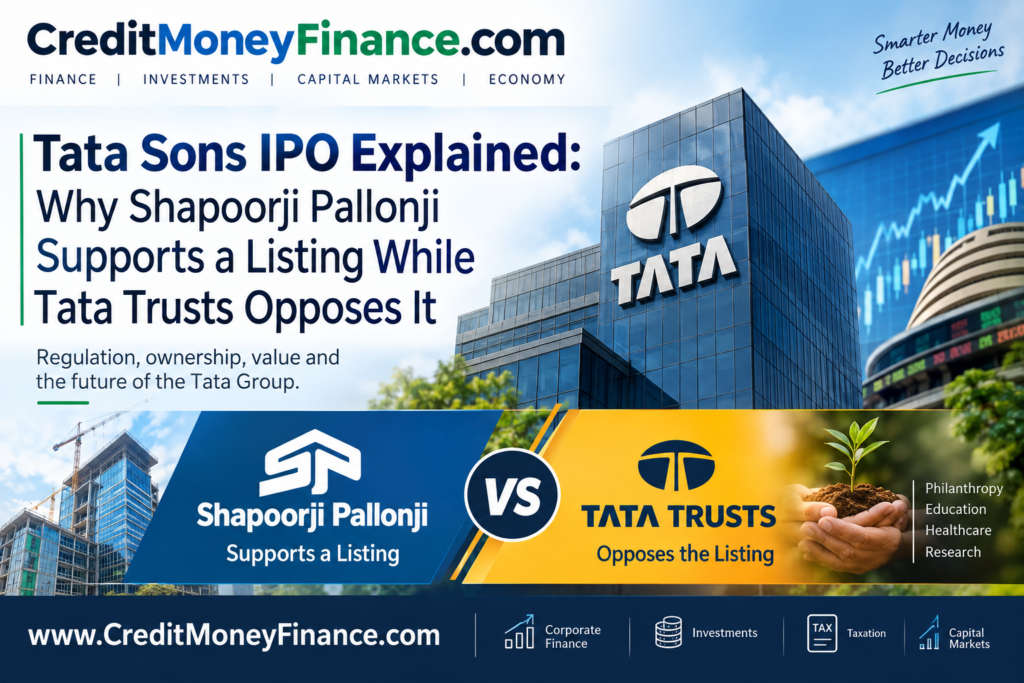
Tata Sons is at the centre of a major corporate and regulatory debate over a potential stock-market listing. Here is why Shapoorji Pallonji supports a listing, why Tata Trusts opposes it, and what the RBI rules mean.
Tata Sons IPO Row: A Battle Over Listing, Ownership, Value and the Future of the Tata Structure
Few corporate developments in India carry the significance of the latest dispute surrounding Tata Sons, the holding company of the Tata Group.
What was once largely a regulatory question about whether Tata Sons would have to become a publicly listed company has now developed into a much broader debate involving shareholder interests, valuation, liquidity, corporate governance, philanthropy and the future structure of one of India’s most important business groups.
At the centre of the issue are two major shareholders with different positions.
The Shapoorji Pallonji (SP) Group, which owns approximately 18.4% of Tata Sons, supports a public listing.
Tata Trusts, which controls approximately 66% of Tata Sons, has maintained that Tata Sons should remain privately held and has asked the company to examine alternatives to a listing.
The situation has become particularly significant after the Tata Sons board moved on September 17 toward a listing, while Tata Trusts publicly reiterated that it had not agreed to the listing.
First, What Exactly Is the Tata Sons IPO Issue?
It is important to make one distinction clear.
Tata Sons is currently a private company. There is no Tata Sons IPO available to investors today.
The current development concerns a potential public listing of Tata Sons, including the possibility of an IPO or another market-listing structure that would allow its shares to be traded publicly.
The final structure, issue size, pricing, timetable and other IPO-related details have not yet been announced.
Therefore, headlines referring to a “Tata Sons IPO” should currently be understood primarily as referring to the proposed listing of Tata Sons, rather than an IPO that investors can presently subscribe to.
Why Is Tata Sons Under Pressure to List?
The regulatory background goes back to the Reserve Bank of India’s framework governing large non-banking financial companies.
Tata Sons has been classified by the RBI as an Upper Layer NBFC. The RBI’s framework provides for enhanced regulatory requirements for such entities and includes a mandatory listing requirement for NBFCs in the Upper Layer.
The RBI included Tata Sons in its Upper Layer NBFC list for 2024-25, identifying it as a Core Investment Company.
The issue became more urgent in September 2026 after the RBI rejected Tata Sons’ attempt to surrender its NBFC registration, according to reports. Tata Sons therefore faces renewed regulatory pressure concerning the listing requirement.
Reports indicate that Tata Sons had sought a route that would allow it to remain outside the mandatory listing framework.
That route has now become considerably more difficult.
Why Does Shapoorji Pallonji Want Tata Sons Listed?
The SP Group is Tata Sons’ largest minority shareholder, with approximately 18.4%.
For the SP Group, the issue is not simply about whether Tata Sons should be public.
It is also about liquidity and monetisation of a very large investment.
The SP Group has significant financial obligations and has previously explored ways of monetising part of its Tata Sons holding.
A public listing could create a transparent market for Tata Sons shares and potentially provide the SP Group with a mechanism to monetise some or all of its investment over time.
Recent reports indicate that the SP Group has been considering monetisation of part of its stake, while Tata Trusts has itself tabled a proposal involving the sale of a portion of SP Group’s Tata Sons shares.
On September 18, SP Group Chairman Shapoor Mistry publicly supported the listing route, saying the objective was not a victory for one side but a stronger Tata institution, greater accountability and other broader objectives.
The financial logic is straightforward:
Large private holding → limited liquidity → need for monetisation → potential public listing → publicly traded shares
However, the actual value that the market would assign to Tata Sons would ultimately depend on factors including its underlying assets, cash flows, investments, governance structure, market conditions and the discount or premium investors apply to a holding company.
Why Does Tata Trusts Oppose the Listing?
The position of Tata Trusts is fundamentally different.
Tata Trusts holds approximately 66% of Tata Sons, primarily through the Sir Ratan Tata Trust and Sir Dorabji Tata Trust.
The Trusts have repeatedly maintained that Tata Sons should remain privately held.
In a statement issued on September 17, Tata Trusts said it had not agreed to the listing and asked that all available alternatives be examined rather than treating listing as the only solution.
The Trusts’ argument is closely connected with the unusual ownership structure of the Tata Group.
Unlike a conventional promoter-controlled conglomerate, the majority ownership of Tata Sons is held by charitable trusts.
Those trusts receive dividends from their investments and use their resources for philanthropic activities, including healthcare, education and research.
Tata Trusts has argued that this ownership structure is an important part of the Tata Group’s institutional character and should be preserved.
The Trusts also point out that Tata Sons had previously decided to remain unlisted. According to its September 17 statement, the Tata Sons board had reached a unanimous conclusion in March 2024 that the company should remain unlisted, while the two principal Tata Trusts passed similar resolutions in July 2025.
The ₹25,000-Crore Proposal Adds Another Dimension
An important development has emerged alongside the listing dispute.
Tata Trusts Chairman Noel Tata tabled a proposal concerning the SP Group’s stake at the September 17 Tata Sons board meeting.
According to Tata Trusts, the proposal involves the sale of enough Tata Sons shares held through Sterling Investments Corporation Private Limited and Cyrus Investments Private Limited to generate at least ₹25,000 crore.
The proposal envisages the transaction occurring in two tranches over 18 months, along with a selective capital-reduction process involving Tata Sons.
This is significant because it illustrates that a potential solution to the SP Group’s liquidity requirement does not necessarily have to involve a public listing.
In other words, the debate has effectively become:
Should Tata Sons list publicly, or can the SP Group’s liquidity requirement be addressed through a negotiated private transaction?
Why Is the Tata Sons Valuation So Important?
This is perhaps the most interesting financial aspect of the entire story.
Tata Sons is not an ordinary operating company.
It is the principal holding company of the Tata Group and has interests in major businesses across technology, automobiles, steel, consumer products, aviation, financial services and other sectors.
That means valuing Tata Sons involves looking through the holding company at the value of its underlying investments.
But a holding company can trade at a discount to the value of its underlying assets.
This is commonly referred to as a holding-company discount.
Consequently, the theoretical value of Tata Sons’ investments does not automatically translate into the same market value for Tata Sons shares.
This issue could become particularly important if Tata Sons eventually comes to the public market.
What Would a Tata Sons Listing Mean for Investors?
A listing would potentially create a new publicly traded Tata Group investment opportunity.
Investors could, subject to the eventual structure and regulatory approvals, obtain direct exposure to Tata Sons rather than buying individual listed Tata companies.
However, Tata Sons would be fundamentally different from buying shares of an operating company such as Tata Motors or TCS.
An investor in Tata Sons would essentially be investing in the holding-company structure and its portfolio of investments.
The market would therefore have to determine how much it is willing to pay for that structure.
Potential Implications of a Listing
If Tata Sons eventually becomes publicly listed, several developments could follow:
1. Greater market transparency
A listed company would have continuing disclosure and reporting obligations applicable to listed entities.
2. Creation of a market price
Tata Sons shares would potentially have a publicly observable market valuation.
3. Liquidity for existing shareholders
Shareholders could potentially have greater flexibility in monetising their holdings, subject to applicable regulations and lock-in or other restrictions.
4. Greater scrutiny
A public company faces regular scrutiny from institutional investors, analysts, shareholders, regulators and the wider market.
5. Possible impact on Tata Group ownership dynamics
A public market could introduce additional shareholders into Tata Sons’ ownership structure.
However, the extent of any change would depend on the final issue structure.
Could the Tata Sons IPO Become One of India’s Biggest Listings?
It is too early to answer that definitively.
The eventual size of any offering would depend on:
- The percentage of shares offered
- Whether the issue consists of fresh shares, an offer for sale, or a combination
- Regulatory requirements
- Existing shareholders’ decisions
- Valuation
- Market conditions
- Investor demand
- The final listing structure
Therefore, estimates circulating in the market should not be treated as the final IPO valuation until Tata Sons formally discloses the relevant details.
The Bigger Issue: Tata Sons Is More Than a Holding Company
This is what makes the current situation particularly unusual.
For most companies, an IPO is primarily a financial transaction.
For Tata Sons, the question has an additional institutional dimension.
The company sits at the centre of a business group whose ownership model has historically linked commercial enterprises with charitable trusts.
Tata Trusts has therefore argued that changing Tata Sons’ ownership structure could have consequences beyond ordinary corporate finance.
The SP Group, meanwhile, has emphasised the potential benefits of listing in terms of liquidity, accountability and institutional development.
These are fundamentally different perspectives on the same corporate structure.
What Happens Next?
Several questions remain unanswered.
1. Will Tata Sons actually proceed with an IPO?
The board has moved toward a listing, but the process still involves regulatory, legal and corporate steps.
2. Will Tata Trusts accept the listing route?
As of September 18, 2026, Tata Trusts has publicly maintained its opposition to listing and has called for alternatives to be examined.
3. Will the SP Group sell part of its stake privately?
The ₹25,000-crore proposal provides one potential route, although the final outcome remains uncertain.
4. What valuation will the market assign to Tata Sons?
This could become one of the biggest questions for investors if a listing proceeds.
5. How will the Tata Group’s governance structure evolve?
The listing dispute has emerged alongside disagreements regarding Tata Sons’ leadership and governance, making the issue broader than a conventional capital-markets transaction.
Tata Sons IPO: The Key Numbers at a Glance
| Particular | Current position |
|---|---|
| Company | Tata Sons Private Limited |
| Status | Privately held |
| Major shareholder | Tata Trusts |
| Tata Trusts’ holding | Approximately 66% |
| SP Group holding | Approximately 18.4% |
| Regulatory classification | Upper Layer NBFC / Core Investment Company |
| Listing issue | Under active consideration |
| SP Group position | Supports listing |
| Tata Trusts position | Opposes listing and seeks alternatives |
| Proposed SP monetisation route | At least ₹25,000 crore, according to Tata Trusts |
| IPO price | Not announced |
| IPO date | Not announced |
| Retail subscription | Not open |
The ownership figures and current positions are based on recent company and regulatory reporting; the eventual transaction structure may change.
What This Means for the Indian Capital Market
The Tata Sons episode could become an important case study in the interaction between corporate ownership, regulation and capital markets.
It raises a larger question for India’s corporate sector:
How should very large privately controlled holding companies balance regulatory requirements, shareholder liquidity, governance considerations and long-term institutional objectives?
The answer in Tata Sons’ case could have implications well beyond the Tata Group.
For investors, however, the most important point at present is to separate the possibility of a Tata Sons IPO from an actual IPO announcement.
There is currently no public issue open for subscription.
The regulatory and board-level developments are moving the company closer to a potential listing, but the eventual structure, valuation, timing and investor opportunity remain matters to be determined.
Conclusion
The Tata Sons listing controversy is not simply a disagreement over an IPO.
It represents a clash of financial, regulatory and institutional considerations.
For the Shapoorji Pallonji Group, a listing could provide a transparent mechanism for unlocking value from its substantial Tata Sons investment.
For Tata Trusts, the central concern is preserving the distinctive ownership model through which charitable trusts control Tata Sons and use investment income to support philanthropic activities.
Meanwhile, the RBI’s regulatory framework has added another layer of urgency to the issue.
The coming months could therefore be crucial for Tata Sons, its shareholders, the Tata Group and India’s capital markets.
One thing is clear: if Tata Sons eventually reaches the stock market, it would not merely be another large Indian IPO. It would represent a significant change in the ownership and financial architecture of one of India’s most prominent business groups.
About CreditMoneyFinance.com
CreditMoneyFinance.com brings readers analysis and insights on corporate finance, investments, taxation, credit, capital markets, startups and India’s evolving financial ecosystem.
More Featured Articles:
Collateral-Free Import Finance in India: Funding Up to USD 5 Million for Growing Businesses.
Revenue-Based Finance in India 2026: The Ultimate Founder’s Guide to Non-Dilutive Growth Capital
Strategic Finance Options for Medical and Hospital Businesses in India (2026)
Personal Finance Red Flags Related To Savings & Emergency Planning
Venture Debt in India: The Complete 2026 Guide for Startups, Founders, CFOs & Growth Companies.