HUF Tax Benefits 2026: Complete Guide to HUF Formation, Tax Saving, Investments & Family Wealth Planning in India
HUF in India: The Most Overlooked Family Tax-Planning Structure – How a Hindu Undivided Family Can Legally Reduce Family Tax and Build Wealth.
Learn how an HUF works in India, who can create an HUF, HUF tax benefits, deductions, investments, formation process and common mistakes. Get expert HUF and tax-planning assistance from Intellex Strategic Consulting Pvt Ltd.
Introduction: Why HUF Still Matters in Modern India
Tax planning is not simply about finding deductions. For business families, entrepreneurs, professionals, investors and property owners, the way family assets and income are legally structured can have a major impact on taxation and long-term wealth creation.
One structure that remains surprisingly underused is the Hindu Undivided Family (HUF).
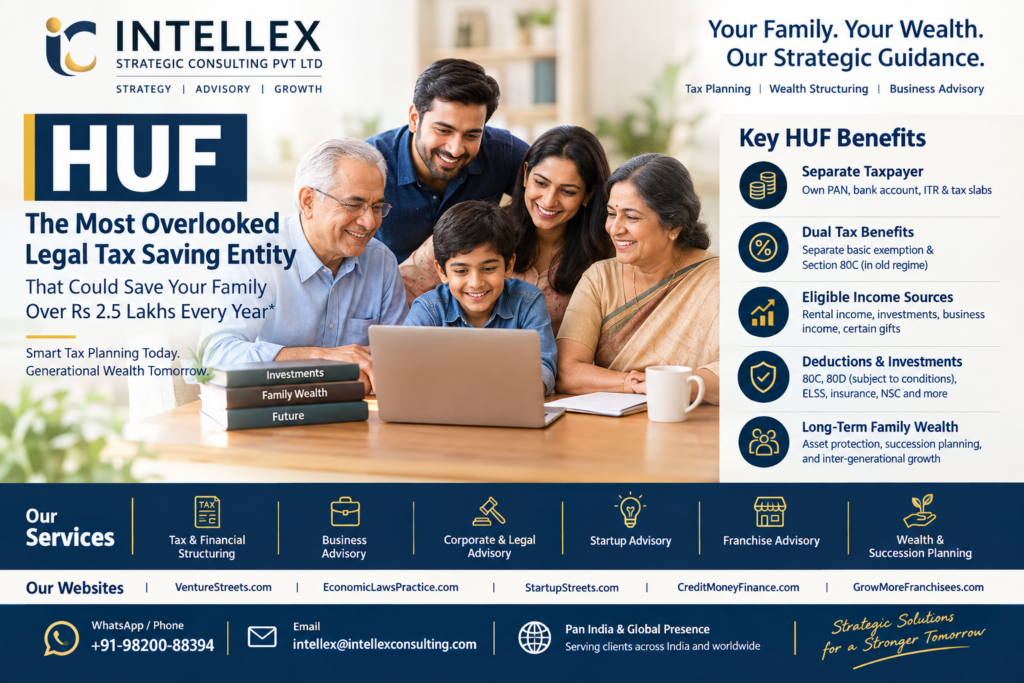
An HUF is recognised as a separate taxable person under Indian income-tax law. Consequently, an HUF can have its own PAN, bank account, investments, income and income-tax return, separate from the individual tax affairs of its members.
The Income Tax Department specifically recognises HUF as a separate entity for taxation purposes.
However, HUF is not a magic tax-saving vehicle. The source of the income, ownership of assets, documentation, tax regime selected and applicable anti-avoidance/clubbing provisions are all important.
This is precisely where professional tax and legal structuring advice becomes valuable.
Intellex Strategic Consulting Pvt Ltd assists entrepreneurs, promoters, investors, professionals and families with strategic tax planning, business structuring, financial advisory and wealth-structuring requirements across India and for internationally connected families and businesses.
1. What Exactly Is an HUF?
HUF stands for Hindu Undivided Family.
It is a family unit recognised under Hindu personal law and taxation law. For income-tax purposes, the HUF can be assessed separately from its individual members.
This distinction is extremely important.
For example, suppose an individual earns income in his or her personal capacity.
That income belongs to the individual.
But if an asset or income genuinely belongs to the HUF and the legal and documentary requirements are satisfied, the income may be taxable in the hands of the HUF instead.
The Income Tax Department’s current guidance expressly treats HUFs as separate taxpayers and provides separate tax slabs for HUFs.
An HUF can have:
- Its own PAN
- Its own bank account
- Its own investments
- Its own income
- Its own books/records where appropriate
- Its own income-tax return
- Its own tax liability
This creates an important family tax-planning opportunity.
2. Who Can Form an HUF?
Traditionally, HUF is associated with Hindu families, but the scope also extends to Jain, Sikh and Buddhist families under the applicable legal framework.
An HUF does not necessarily require a large joint family living under one roof.
The structure and rights of members are governed by applicable personal law, succession rules and tax provisions.
Therefore, before forming an HUF purely for tax purposes, it is important to establish that the proposed HUF has a legitimate legal and financial basis.
3. HUF Is a Separate Taxpayer — But Don’t Misunderstand What That Means
One of the biggest attractions of an HUF is that it is separately assessed for income-tax purposes.
Consider a simplified example.
Suppose:
Individual A:
Personal taxable income = ₹20 lakh
and
HUF:
Legitimate HUF income = ₹10 lakh
The two are not automatically combined merely because A is the Karta or a member.
However, this does not mean that an individual can simply transfer his salary or personal business income to an HUF and make it disappear from personal taxation.
The source and ownership of income are critical.
Professional structuring is therefore much more important than merely opening an HUF bank account.
4. Where Can HUF Income Come From?
Depending upon the circumstances, an HUF may have income from legitimate HUF-owned assets and activities, such as:
1. Ancestral property
Rental income from property genuinely belonging to the HUF can potentially be assessed in the HUF’s hands.
2. HUF investments
An HUF can own and invest in eligible financial assets.
Income generated from those investments can potentially belong to the HUF, subject to applicable tax provisions.
3. HUF-owned business
An HUF can carry on business in appropriate circumstances.
The income-tax return framework specifically recognises HUFs having business/professional income.
4. HUF property transactions
Capital gains arising from the transfer of genuinely HUF-owned assets may be taxable in the HUF’s hands.
5. Certain gifts
Gifts received by an HUF need to be analysed under the applicable provisions of the Income-tax Act, including the relationship/source and applicable exemptions.
This is an area where professional advice is particularly important.
5. The Big Attraction: A Separate Taxpayer
Historically, one of the most important reasons families considered HUFs was the availability of a separate basic exemption and separate tax computation.
This remains relevant.
For AY 2026-27, the Income Tax Department lists separate HUF tax slabs.
Under the new tax regime, HUF tax rates are:
| Total Income | Tax Rate |
|---|---|
| Up to ₹4 lakh | Nil |
| ₹4–8 lakh | 5% |
| ₹8–12 lakh | 10% |
| ₹12–16 lakh | 15% |
| ₹16–20 lakh | 20% |
| ₹20–24 lakh | 25% |
| Above ₹24 lakh | 30% |
These are HUF rates and should not be confused with the tax treatment of resident individuals.
6. A Very Important 2026 Update: HUF Does NOT Get the ₹12 Lakh 87A Rebate
This is one of the most important corrections to many social-media articles about HUF.
For AY 2026-27, the enhanced ₹60,000 Section 87A rebate for income up to ₹12 lakh applies to eligible resident individuals — not HUFs.
Therefore, an HUF should not be assumed to have zero tax merely because its taxable income is below ₹12 lakh.
For example, under the new regime, an HUF with taxable income of ₹12 lakh would ordinarily have tax calculated under the HUF slab structure rather than receiving the individual 87A rebate.
This distinction can materially affect whether HUF structuring is beneficial.
7. What About Section 80C?
This is another area where outdated articles frequently create confusion.
Under the old tax regime, eligible HUF taxpayers can claim the applicable Section 80C deduction, subject to the statutory conditions and aggregate limit.
The Income Tax Department currently states that the combined Section 80C limit is ₹1.50 lakh.
Eligible instruments can include qualifying:
- Life insurance
- Provident Fund
- National Savings Certificate
- Certain investments
- Housing-loan principal
- Eligible tuition fees
- Other specified investments/payments
However, the new tax regime generally does not permit the traditional 80C deduction.
Therefore, tax planning must begin with a comparison of the old and new tax regimes, rather than blindly recommending HUF investments under Section 80C.
8. HUF and Section 80D
HUFs can also potentially claim deductions relating to health-insurance premiums and eligible medical expenditure under Section 80D when the applicable conditions are satisfied.
For example, the Income Tax Department’s AY 2026-27 guidance provides specific Section 80D limits for HUF members.
Again, these benefits need to be considered in conjunction with the tax regime selected.
9. HUF Can Be Useful for Family Wealth Creation
The real value of an HUF can extend beyond immediate tax savings.
For some families, it can become part of a broader family wealth-management framework.
An appropriately structured HUF may hold:
- Property
- Financial investments
- Shares
- Bonds
- Eligible mutual fund investments
- Business interests
- Other permissible assets
The family can then develop a systematic framework for managing these assets.
This can be particularly relevant for:
Entrepreneurial families | Business promoters | Property-owning families | Investors | Professionals | Multi-generational families
10. HUF and Family Business
HUF can also be relevant where a family has an established business tradition.
For example, a family may have:
- Ancestral business assets
- Family-owned property
- Existing investments
- Multiple generations participating in the family enterprise
The HUF structure can sometimes form part of the overall ownership and succession architecture.
But it should never be inserted into an existing business structure without examining ownership, capital contribution, succession, GST, Companies Act, partnership/LLP implications and income-tax provisions.
This is why professional advice matters.
11. How Do You Create an HUF?
An HUF does not operate exactly like incorporating a private limited company.
There is no equivalent process of incorporating an HUF with the Registrar of Companies.
A typical practical process involves:
Step 1 — Establish the family/HUF structure
Determine the Karta and members and document the constitution appropriately.
Step 2 — Prepare HUF documentation
An HUF declaration/deed is commonly prepared to document the HUF’s existence, Karta and members.
Step 3 — Obtain PAN
The HUF needs its own PAN for income-tax purposes.
Step 4 — Open an HUF bank account
The bank account should be maintained distinctly from the Karta’s personal account.
Step 5 — Identify HUF assets and income
Only assets and income that legitimately belong to the HUF should be treated as HUF assets/income.
Step 6 — Maintain proper documentation
Investment records, property documents, bank transactions, gifts, capital contributions and tax returns should be properly maintained.
Step 7 — File the appropriate income-tax return
The applicable ITR depends on the nature and source of income. The Income Tax Department provides separate filing provisions for HUF taxpayers.
12. The Biggest Mistake: Simply Transferring Personal Income to HUF
This is where many internet articles oversimplify HUF tax planning.
You cannot simply say:
“I earn ₹30 lakh, so I will transfer ₹10 lakh to my HUF and pay less tax.”
The tax consequences depend upon how the asset or income originated.
There are specific provisions dealing with clubbing and transfers of assets to HUFs.
Therefore, the question should not be:
“How much income can I transfer to my HUF?”
The correct question is:
“Which assets and income can legally and tax-efficiently belong to my HUF?”
That is a completely different approach.
13. HUF Is Not a Tax Evasion Tool
A properly structured HUF is a legitimate component of Indian tax and family-wealth planning.
But artificial transactions, incorrect ownership declarations, circular transactions or attempts to disguise personal income as HUF income can create serious tax problems.
Therefore:
Tax planning = legal structuring.
Tax evasion = concealment or misrepresentation.
They are not the same thing.
Intellex Strategic Consulting Pvt Ltd focuses on compliant and commercially practical structuring, rather than aggressive arrangements that could create unnecessary tax or legal exposure.
14. HUF and Real Estate
Real estate is one of the areas where HUF planning can become particularly relevant.
Families may have:
- Ancestral residential property
- Commercial property
- Agricultural land
- Rental properties
- Multiple family-owned assets
Before deciding whether an asset should belong to an HUF, however, the family should examine:
- Original ownership
- Source of acquisition
- Succession history
- Existing title
- Capital gains implications
- Stamp duty
- Transfer implications
- Income-tax consequences
- Future succession
A property should not be transferred merely because someone has heard that “HUF saves tax.”
15. HUF and Investments
An HUF can be an important investment-holding structure where legally appropriate.
Potential investment areas may include:
- Equity shares
- Mutual funds
- Bonds
- Fixed-income products
- Government securities
- Property
- Other permissible investments
The investment strategy should be based on:
Tax efficiency + risk management + liquidity + succession planning + long-term wealth creation.
Tax savings should not be the only objective.
16. HUF for Entrepreneurs and Business Families
For entrepreneurs, HUF planning can be particularly interesting because family wealth often extends beyond salary income.
A business promoter may have:
- Personal investments
- Family investments
- Ancestral assets
- Rental income
- Business interests
- Capital-market investments
- Multiple generations involved in wealth management
A professional advisor can examine whether some assets or activities are appropriately structured within an HUF while maintaining legal and tax compliance.
17. HUF and Succession Planning
Perhaps the most overlooked benefit of HUF is that it is not simply a “tax-saving product.”
It can also be part of family succession and inter-generational wealth planning.
Families should consider:
- Who owns the assets?
- Who manages them?
- Who receives income?
- What happens when the Karta changes?
- What happens when a family member is added?
- What happens upon death?
- How will disputes be prevented?
- What documentation should be maintained?
For wealthy families, these questions can be much more important than saving a few lakh rupees of tax.
18. Is HUF Suitable for Everyone?
No.
HUF may be particularly worth examining where there is:
- Ancestral property
- Family wealth
- Rental income
- Family investments
- A family business
- Multiple generations
- Significant taxable income
- Long-term succession requirements
It may be less attractive where:
- There are no meaningful HUF assets
- The structure would have no genuine income source
- Administrative complexity outweighs benefits
- The new tax regime makes the expected deductions less useful
- The family does not want additional compliance
The right answer depends on the family’s actual circumstances.
19. HUF Tax Planning Should Be Compared Under Both Tax Regimes
This is especially important in 2026.
The new tax regime has significantly changed the tax-planning landscape.
For HUFs, the traditional deductions associated with the old regime may not be available under the new regime. The Income Tax Department’s current guidance specifically lists the applicable HUF deductions and the tax-regime framework.
Therefore, a professional HUF review should compare:
Old Regime vs New Regime
based on:
- Total HUF income
- Nature of income
- Investments
- Insurance
- Property
- Business income
- Deductions
- Capital gains
- Applicable exemptions
- Long-term family objectives
20. How Much Can an HUF Actually Save?
There is no universal ₹2.5 lakh annual saving.
That figure depends entirely on the family’s income structure, eligible HUF income, deductions, tax regime and applicable provisions.
For one family, HUF structuring could provide meaningful tax and wealth-planning benefits.
For another, the benefit could be relatively small.
The correct approach is therefore to perform a family-specific tax computation rather than promoting a fixed savings number.
This makes HUF planning more credible, compliant and commercially useful.
21. HUF Due Diligence Checklist
Before establishing or restructuring an HUF, consider reviewing:
Legal
- Family constitution
- Karta
- Members
- Coparceners
- Succession position
- Existing ownership documents
Tax
- Personal income
- HUF income
- Existing deductions
- Tax regime
- Capital gains
- Clubbing provisions
- Gift taxation
Financial
- Property
- Investments
- Bank accounts
- Business interests
- Insurance
- Existing liabilities
Documentation
- HUF declaration
- PAN
- Bank account
- Property records
- Investment statements
- Gift documentation
- Tax returns
22. Why Professional HUF Advisory Matters
HUF planning sits at the intersection of:
Taxation + Family Law + Wealth Management + Property + Investments + Business Structuring + Succession Planning.
A simple online article cannot determine whether an HUF is appropriate for a particular family.
That requires analysis of the actual facts.
This is where Intellex Strategic Consulting Pvt Ltd can assist.
Intellex Strategic Consulting Pvt Ltd — Strategic Advisory Across India & Globally
Intellex Strategic Consulting Pvt Ltd provides strategic consulting and advisory support to entrepreneurs, promoters, investors, businesses, family-owned enterprises and professionals.
Our advisory approach can cover:
Tax & Financial Structuring
- HUF advisory
- Family wealth structuring
- Tax planning
- Investment structuring
- Business financial planning
Business Advisory
- Business restructuring
- Strategic planning
- Capital raising
- Debt advisory
- Investor readiness
- Business expansion
Corporate & Legal-Commercial Advisory
- Business structuring
- Transaction advisory
- Due diligence coordination
- Corporate strategy
- Commercial negotiations
Entrepreneur & Startup Advisory
- Startup strategy
- Fundraising preparation
- Investor connect
- Business planning
- Growth strategy
Franchise Advisory
Through GrowMoreFranchisees.com, Intellex also supports entrepreneurs and investors evaluating franchise opportunities and business expansion.
Serving Clients Across India and Internationally
Intellex Strategic Consulting Pvt Ltd is positioned to work with clients across:
Mumbai | Delhi NCR | Bengaluru | Hyderabad | Chennai | Pune | Ahmedabad | Kolkata | Jaipur | Indore | Surat | Kochi | Chandigarh | Other Indian Markets
and with internationally connected entrepreneurs, investors, promoters and families.
For cross-border matters, the precise scope of Indian tax, FEMA, foreign-tax and local-jurisdiction advice should always be determined with the relevant qualified professionals.
Connect With Intellex Strategic Consulting Pvt Ltd
If you are considering:
HUF Formation | HUF Tax Planning | Family Wealth Structuring | Business Tax Planning | Investment Structuring | Business Advisory | Capital Raising | Startup Advisory | Franchise Advisory
speak with the Intellex Strategic Consulting Pvt Ltd team for an initial discussion of your requirements.
WhatsApp / Phone
+91-98200-88394
intellex@intellexconsulting.com
Our Websites
VentureStreets.com
EconomicLawsPractice.com
StartupStreets.com
CreditMoneyFinance.com
GrowMoreFranchisees.com
Final Takeaway
HUF remains a potentially valuable structure for eligible Indian families, but modern HUF tax planning requires much more than simply obtaining a PAN and opening a bank account.
The most important questions are:
Does the family have genuine HUF assets?
Can the income legitimately belong to the HUF?
Which tax regime is more efficient?
Are deductions actually available?
Are clubbing and transfer provisions being handled correctly?
Does the structure also support long-term family wealth and succession planning?
The answer will be different for every family.
For that reason, the objective should not be to create an HUF merely because someone promises a fixed ₹2.5 lakh tax saving. The objective should be to determine whether a properly documented HUF forms part of an efficient, legally compliant and sustainable family wealth strategy.
Intellex Strategic Consulting Pvt Ltd can assist families, entrepreneurs and business promoters in evaluating these issues and developing a practical strategy based on their individual circumstances.
Disclaimer: This article is for general educational and informational purposes and should not be treated as individual tax, legal or investment advice. HUF taxation can depend on the facts, source and ownership of assets, applicable tax regime and current law. Professional advice should be obtained before creating, transferring or restructuring HUF assets.
More Featured Articles:
Singapore’s 15% Minimum Tax Is Changing How Multinationals Structure Their Operations in Asia.
Income Tax Form 104: A Complete Guide to the New NPO Registration Process in India (2026).
8 Types of Tax-Free Income in India You Must Know (2026 Guide for Smart Tax Planning)
How to Analyse a Venture Capital Fund: A Deep-Dive Framework for LPs and Founders.